VentureEdu Logo
VentureEdu

Blog

Unlock Insights with Us

Stay informed with the latest trends, insights, and strategies to drive innovation and business growth

The Insights

Startup Idea Validation Checklist for First-Time Founders
EntrepreneurshipSEP 16, 2026

Startup Idea Validation Checklist for First-Time Founders

A startup idea validation checklist is a fixed sequence of evidence gates your idea has to clear before you spend real money building it. Each gate asks for proof of customer behaviour instead of an opinion, and each carries a pass mark you decide in advance. Five gates cover a first-time founder in India: a written problem statement, ten conversations with people who can actually buy, a paid commitment, a channel you can repeat, and unit economics that survive Indian price sensitivity. Work through them in order, and stop at the first gate you cannot clear.What is a startup idea validation checklist?A validation checklist converts a founder's belief into a testable sequence. Instead of asking whether the idea sounds good, it asks what evidence would have to exist if the idea were true, then goes looking for that evidence. The checklist format matters because it forces the order: problem before solution, buyer before build, payment before scale. Founders who skip the order usually end up validating a product nobody asked for.The unit of proof throughout is behaviour, not sentiment. A prospect who says the idea is brilliant has cost you nothing and told you nothing. A prospect who blocks 30 minutes for a demo, shares their current workaround in detail, or transfers ₹500 as an advance has spent something, and spending is what separates polite interest from demand. Every checkpoint below is written to demand that kind of costly signal.What a checklist cannot do is decide for you. It sets thresholds, records what happened, and makes the decision honest by taking the judgement call out of the moment when you are emotionally invested. The value sits in writing your pass mark down before the test runs, because a threshold set afterwards will always be set exactly where the results landed.Why does a checklist beat founder instinct?India's startup base is now large enough that the odds are visible in public data. DPIIT-recognised startups crossed 2.23 lakh as of 31 March 2026, after a record 55,200 recognitions in FY26 alone. The other half of that record is less quoted. As of 31 January 2026, the Ministry of Corporate Affairs classified 6,789 recognised startups as closed, meaning dissolved or struck off.Closures rarely trace back to a bad product. They trace back to a founder who never confirmed that a specific group of people had the problem, disliked their current fix, and would pay to change it. Capital shortage is usually the symptom. The cause sits earlier, in an assumption that went untested for eighteen months because testing it felt slower than building.Instinct is not worthless here. It is what generates the idea and picks which assumption to attack first. It just makes a poor referee. The checklist exists to referee. If you want the reasoning behind each gate rather than the checklist itself, our longer guide on how to validate a startup idea in India covers the underlying method in depth.What are the five checkpoints in the validation checklist?Each checkpoint is a gate, not a task to tick and move past. You clear it or you fix what failed.Write the problemOne sentence: State who has the problem, how often it occurs, and what it costs them in money, time, or risk.Named segment: Replace broad labels like small businesses or students with a group you could list 50 names from.Current fix: Write down what they use today, including spreadsheets, an agent, a WhatsApp group, or doing nothing.Kill condition: Decide now what result would make you abandon this idea.Find ten buyersRight people: Talk to people who match the segment and control the decision, not the friends who will encourage you.Past behaviour: Ask about the last time the problem occurred and what they did, rather than what they would do.No pitching: Describe the solution only after they have described the pain, so you do not lead the answer.Repeat patterns: Look for the same complaint in the same words across at least six of the ten.Ask for moneyReal price: Name a specific rupee figure instead of asking whether they would pay something.Costly action: Request a deposit, an advance booking, a paid pilot, or a signed intent, not a free waitlist signup.Budget owner: For B2B, confirm who approves spend and whether a budget line already exists.Refusal reasons: Record why people declined, because the objection tells you more than the acceptance.Prove the channelOutside network: Reach at least ten prospects who have no connection to you or your college batch.Repeatable source: Identify one channel that produced qualified interest twice, whether that is search, a trade association, a reseller, or a community.Cost per lead: Run a small paid test, ₹2,000 is enough for direction, and record cost per qualified enquiry.Second attempt: Confirm the channel still works when you are not personally present in the conversation.Check the mathsDelivery cost: Calculate what one unit costs to deliver, including labour, returns, refunds, and support.Acquisition cost: Compare that against what a customer cost you to acquire in the channel test.Repeat rate: Estimate how many times a customer buys before they leave, using pilot behaviour rather than hope.Compliance floor: List the registrations, licences, or GST obligations the model triggers before you scale it.What Counts as a Pass on Each Checkpoint?Thresholds turn a checklist into a decision tool. Set yours before the test, and treat a maybe as a fail.Start with the problem itself. If you need three paragraphs to explain the pain, the problem is probably not yet clear enough. A pass is when a stranger can understand the problem in one sentence and repeat it back correctly.Next, find ten buyers. Compliments and general agreement are weak signals; what matters is whether people independently describe the same problem. A useful threshold is for six out of ten people to describe the same problem without being prompted.Then, ask for money. Free signups or people saying they are “definitely interested” do not demonstrate willingness to pay. A stronger signal is three paid commitments at a real price.You also need to prove the channel. Sales that come only from friends and family tell you little about whether the business can acquire customers repeatedly. A pass means generating ten qualified leads from one repeatable source.Finally, check the maths. Do not wait until after launch to work out whether the economics make sense. At the price you are testing, the business should have positive contribution.Three paid commitments is deliberately a low bar. The goal is not to prove that the business works; it is to prove that strangers will part with money before you have built anything. If you cannot get three people to pay, that is useful information to have early. Finding that out in week six is the entire return on the exercise.Which checks are specific to Indian founders?Global validation templates were written for markets where price sensitivity is lower and distribution is thinner. Four adjustments matter here.Rupee anchoring: Test the price in rupees against the substitute your customer already pays for, since a low price does not automatically raise conversion and can weaken trust in service categories.City spread: Validate in the specific city or tier where you will actually sell, because metro feedback and Tier 2 behaviour diverge sharply on payment habits and delivery expectations.Approval chains: Identify the real decision maker, who may be a family member, a procurement head, or a distributor rather than the user in front of you.Offline reality: Check whether the transaction happens online at all, because many Indian categories still close over a phone call, a shop counter, or a WhatsApp thread.Compliance timing: You do not need full registration to test demand, but you should know what the model will require at scale. A startup legal checklist covers the registrations and filings that follow validation.How do you score the checklist and decide what to do next?Score one point per checkpoint cleared at its pass mark, and act on the total rather than on the most encouraging conversation you had.Five of five: Build the smallest possible version around the behaviour you proved, and nothing else.Four of five: Narrow to the segment that responded strongest, then retest only the failed gate.Three of five: Change one major assumption, usually the segment or the price, and run the checklist again.Two or fewer: Stop, write up what you learned, and keep the notes. The problem may be real and the timing wrong.The written record matters beyond your own decision. Interview patterns, paid pilot results, and cost per qualified lead are exactly what a seed investor asks for, and they populate the traction and market slides in a pitch deck for investors in India. Founders who validate loosely end up reconstructing this evidence under deadline. If your score sits at three or lower and the problem still looks real, a startup incubator in India is usually a better next step than a build.What mistakes make a validation checklist useless?Friendly sample: Interviewing your own network produces encouragement, not evidence.Leading questions: Asking whether someone would use your app invites a yes with no cost attached.Moving thresholds: Setting the pass mark after seeing results converts the checklist into a formality.Feature drift: Testing which features people prefer before confirming the problem deserves a product.Survey reliance: Treating form responses as demand when nobody was asked to spend anything.Single city: Reading one metro's behaviour as national when language, income, and trust differ across markets.Where do first-time founders get help working through this?Most first-time founders can run the first two checkpoints alone. The later ones, pricing tests, channel economics, and the decision to stop, benefit from someone who has seen the same signals go wrong before. Structured programs exist for exactly this stage of the work.VenturEdu, India's first full-time residential venture school, was launched by the Gurugram-based venture platform Fibonacci X and founded by Kulmani Rana. Its V-Unit model assigns every idea a five-member mentor group covering go-to-market, finance, brand, sector expertise at Series A and above, and academic-industry input, which means validation decisions get reviewed by people with no stake in your optimism. Founders who join the PGP in Entrepreneurship run this evidence-gathering with that structure around them, then take the results into demo days in front of a 100-plus investor network.The checklist still belongs to you. Nobody else can do the ten conversations, and no mentor can make a customer pay. What structure changes is how honestly the results get read.The bottom lineValidation is not a research phase you exit once. It is a sequence of small, cheap bets that each buy you the right to spend more. Write the problem in one sentence, talk to ten real buyers, ask three of them for money, prove one channel works outside your network, and check that the maths holds at the price you tested. Clear five gates and build. Clear three and change something. The founders who survive their first year are rarely the ones with the best idea, they are the ones who found out fastest.If you want operator guidance while you work through validation, book a consultation with the VenturEdu team.Frequently asked questionsWhat is included in a startup idea validation checklist?A complete checklist covers five gates: a one-sentence problem statement tied to a named segment, ten customer conversations about past behaviour, a test of willingness to pay at a real price, proof of one repeatable acquisition channel outside your network, and unit economics that stay positive at the tested price.How long does it take to complete a validation checklist?Most first-time founders can work through all five gates in four to eight weeks. B2C ideas move faster because buying decisions are individual. B2B and offline ideas take longer, since procurement cycles, distributor conversations, and pilot approvals add weeks that cannot be compressed.How many customer interviews are enough to validate an idea?There is no fixed number, but ten conversations with the right segment is a practical starting bar. What matters is repetition: if six of ten describe the same problem in similar language without being prompted, you have a pattern. If ten produce ten different answers, your segment is still too broad.Can you validate a startup idea without spending money?Yes for the first three gates. Problem definition, customer interviews, and asking for a paid commitment cost only time. The channel test usually needs a small budget, around ₹2,000 to ₹5,000, to produce a reliable cost per qualified enquiry rather than a guess.What is the difference between idea validation and market research?Market research describes a market: size, trends, competitors, and demographics. Idea validation tests whether specific people will change their behaviour and pay you. Research tells you the category exists. Validation tells you whether your version of it has a customer.Does a validation checklist work for service businesses?Yes, and the paid gate is often easier to clear. Service founders can sell the work manually before any system exists, delivering by phone, spreadsheet, or WhatsApp. A paid consultation, a booking advance, or a repeat engagement is strong evidence, since the customer is buying an outcome rather than a promise.What should you do if your idea fails the checklist?Identify which gate failed and change only that variable. A failed problem gate usually means the wrong segment. A failed payment gate often means the wrong price or the wrong buyer. A failed channel gate means the demand may be real but unreachable at a viable cost. Abandon the idea only when the problem itself ranks low for everyone you spoke to.Do investors ask to see validation evidence?Yes. Early-stage Indian investors ask for interview patterns, segment definition, demand test results, paid pilots, activation, and repeat usage. Evidence gathered during validation becomes the traction narrative in a seed conversation, which is why the record is worth keeping in writing from the first interview onward.

VenturEdu
VenturEdu
Read Full Entry
MVP for Startups in India: What to Build, What to Skip, and What It Should Prove
EntrepreneurshipSEP 14, 2026

MVP for Startups in India: What to Build, What to Skip, and What It Should Prove

An MVP is the smallest version of your product that can test one risky assumption with real users. It is not a cheap version of the full product, and it is not a first release. Judge it by the decision it lets you make, not by how much of your roadmap it covers. For most Indian founders that means a build of four to eight weeks, one core workflow, and a clear pass mark agreed before the first line of code. If you cannot name the assumption your MVP is testing, you are not building an MVP. You are building a product early.What is a minimum viable product?A minimum viable product is a deliberately incomplete build whose purpose is learning rather than revenue. The word doing the work in that phrase is viable. The build has to be complete enough that a real user can finish a real task and get a real outcome, because anything less produces feedback about the gaps rather than about the idea. A landing page that promises a service nobody can actually receive tells you about your copywriting, not your market.The confusion that costs founders the most money is treating minimum as a budget instruction. Minimum refers to scope, not quality. One workflow, built properly, teaches you more than six workflows built badly, because users abandon broken software before they reveal whether they wanted it. The reduction happens across features, not across craft.What follows from this is uncomfortable for anyone who enjoys building. An MVP that succeeds may still get thrown away. Its output is evidence, and evidence is worth having even when it kills the plan. Founders who treat the MVP as version one of the real product tend to defend it long after the data has stopped supporting it.How Is an MVP Different From a Prototype or a Proof of Concept?These three terms are often used interchangeably in Indian founder conversations, but they answer three different questions. Getting the label wrong can mean spending time and money building the wrong thing.A proof of concept (PoC) answers the question: Can this be built at all? It is primarily a technical exercise, usually conducted internally by the engineering team. The effort can range from a few days to around two weeks, and the result typically never leaves the building.A prototype answers a different question: Does this flow make sense to a user? It is often clickable and designed to simulate the product experience, but may have little or no working backend. Test users interact with it in a controlled session, usually with the founder or team guiding them. A prototype typically takes around one to three weeks to create.An MVP, or minimum viable product, answers the question that matters for demand: Will real users adopt and pay for this? Unlike a prototype, an MVP is put in the hands of actual customers, who should be able to use it without the team standing over them. A typical MVP can take four to twelve weeks to build, depending on the product.The distinction is simple: a proof of concept tests technical feasibility; a prototype tests user comprehension and flow; an MVP tests real-world adoption and willingness to pay.A proof of concept is a technical answer and generally never needs to leave the building. A prototype is a way to test whether the experience makes sense. Only the MVP reaches someone with their own problem and no obligation to be nice to you. If your build never reaches that third stage, you have not tested demand whatever you choose to call the artefact.What should your MVP actually prove?Write the pass mark down before the build starts, in the same document as the scope. Thresholds set afterwards get set exactly where the results happened to land.One assumption: Name the single belief that, if wrong, makes the whole business unviable, and design the build around testing it.Unsupervised activation: Users complete the core action without you sitting beside them explaining it.Return behaviour: People come back after the novelty of the first attempt has worn off.Payment evidence: Someone pays, renews, or approves a budget at a price you can actually sustain.Delivery load: You learn what the work costs to fulfil, including support, refunds, and the manual steps you hid from users.That last point is where Indian service and marketplace models most often break. The software works, and the operations behind it cost three times what the pricing assumed. This is also the earliest moment you can put real numbers into a model, which is why founders who have already worked through unit economics for startups get more out of a pilot than founders who calculate margins afterwards.What does an MVP cost and how long should it take in India?Indian development agencies quote a wide band, and the spread tells you more about scope discipline than about market rates. Published ranges run from roughly ₹50,000 for a landing page test to ₹25 lakh or more for a full multi-role platform, with most agency guides settling around ₹5 lakh to ₹12 lakh for what they describe as a scalable MVP. Timelines cluster at four to eight weeks for simple builds and eight to fourteen weeks for anything with multiple integrations.Read those numbers carefully. Almost every source publishing them sells MVP development, so the ranges describe what agencies build, not what founders need. The useful question is not what an MVP costs. It is which of these three you actually require.Landing page testA page describing the outcome, a way to express intent, and nothing behind it. Appropriate when your risky assumption is whether anyone wants this at all. Cheap, fast, and frequently sufficient. Many founders skip it because it feels unserious, then spend eight lakh learning the same thing.Manual deliveryYou deliver the service by hand through WhatsApp, calls, and spreadsheets while presenting a simple front end. Appropriate when the assumption is whether the outcome is valuable, not whether it can be automated. This is the highest-learning, lowest-cost option in Indian service categories, and it produces paying customers rather than signups.Custom buildReal software with one workflow, built when the assumption genuinely requires software to test, for example anything involving real-time data, multiple user roles, or regulated flows. Justified for most B2B SaaS. If you are heading this way, our guide on how to start a SaaS startup in India covers the wider setup around the build.When should you not build an MVP at all?Skipping the build is a legitimate outcome and an underused one.Untested problem: You have not confirmed that a specific group has this problem often enough to act on it.No named buyer: You cannot list twenty real people or companies who would use the first version.Unreachable users: You have no channel to put the build in front of anyone outside your own network.Software optional: The service can be delivered manually today, in which case deliver it manually and learn faster.Investor theatre: The only reason to build is that a deck feels thin without a product screenshot.Each of those is a validation problem, not a product problem, and building will not fix it. Work through how to validate a startup idea in India first, because every one of these gaps gets cheaper to close before a build than after one.What should you cut from the first version?Cut anything that exists to make the product look finished rather than to test the assumption. In practice that means the admin dashboard, the settings page, the onboarding tour, the second user role, the integrations nobody asked for, the mobile app when a responsive web page would do, and every notification type except the one that brings people back.Cut automation hardest of all. If ten users need a report generated, generate it yourself at night. The manual version teaches you what the automated version should do, and it costs a fraction of building the wrong automation confidently.What survives the cut is usually smaller than founders expect, which is the point. A scope you can ship in six weeks keeps you in the market while you still have money to act on what you learn.How do you know whether the MVP worked?Judge it on behaviour after the first week, when curiosity has stopped inflating the numbers.Activation rate: The share of users who complete the core action at least once without help.Return rate: Users who come back in week two, which separates interest from utility.Conversion to payment: People who move from free use to a real transaction at your tested price.Support load: The volume and type of questions, which reveals where the product fails to explain itself.Referral signal: Users who bring someone else without being asked, the strongest early signal there is.None of these individually means product-market fit, and treating them as if they do is how founders scale a business that has not earned it yet. Our guide to product-market fit for startups sets out what the real threshold looks like and why an MVP that performs well is only the first evidence of it.Where do founders get help scoping an MVP?Scoping is where first-time founders lose the most money, and it is difficult to do alone because every instinct pushes toward building more. An outside reviewer who has no stake in the build being impressive is worth more at this stage than a better developer.VentureEdu, India's first full-time residential venture school, was launched by the Gurugram-based venture platform Fibonacci X and founded by Kulmani Rana. Its V-Unit model puts a five-member mentor group around each venture, including a go-to-market specialist and a sector mentor with Series A and above experience, which means scope decisions get argued with someone who has watched an over-built first version fail before. Founders on the PGP in Entrepreneurship run this build-and-test cycle inside a 14-month programme rather than in isolation.The bottom lineAn MVP is a test with a build attached, not a product with features removed. Name the assumption, pick the cheapest format that can honestly test it, agree the pass mark in advance, ship in weeks rather than months, and read the results after the novelty has worn off. Most Indian founders who regret their first build regret its size, not its quality. Build the smallest thing that could tell you the truth.If you want experienced operators reviewing your scope before you commit a budget, book a consultation with the VenturEdu team.Frequently asked questionsWhat is an MVP in a startup?An MVP, or minimum viable product, is the smallest working version of a product that lets real users complete a real task, built to test one risky assumption. Its purpose is learning rather than revenue, and it is judged by the decision it enables rather than by how much of the roadmap it delivers.How much does it cost to build an MVP in India?Published agency ranges run from around ₹50,000 for a landing page test to ₹25 lakh or more for a complex platform, with most guides quoting ₹5 lakh to ₹12 lakh for a scalable build. Those figures come from firms selling development, so treat them as a menu rather than a requirement. Many assumptions can be tested for far less.How long should it take to build an MVP?Four to eight weeks for a simple build, and eight to fourteen weeks for a product with multiple integrations or user roles. If the timeline stretches past three months, the scope has grown beyond what an MVP is for, and the build has quietly become version one of the product.What is the difference between an MVP and a prototype?A prototype is usually clickable with no working backend, and it tests whether a user understands the flow while you watch. An MVP works end to end and goes to real customers unsupervised, testing whether they adopt it and pay. A prototype tests comprehension, an MVP tests demand.Can you build an MVP without writing code?Yes, and for many Indian service and marketplace ideas it is the better choice. Delivering manually through WhatsApp, forms, calls, and spreadsheets behind a simple front end tests whether the outcome is valuable without testing whether you can automate it, and it produces paying customers rather than signups.What features should an MVP include?One core workflow, built well enough that a user can finish it alone, plus whatever is genuinely required to deliver the outcome. Leave out admin dashboards, settings pages, secondary user roles, onboarding tours, and most integrations. If a feature does not affect the assumption you are testing, it does not belong in the first version.What metrics show that an MVP is working?Activation without assistance, return usage in week two, conversion to a real payment at your tested price, and unprompted referrals. Signups and downloads are not evidence. The signal you want is behaviour that continues after the initial curiosity fades.Do investors expect an MVP before seed funding?Not always, but they expect evidence. An MVP is one way to produce it, and for pre-product founders a paid pilot or a manually delivered service can carry the same weight. What investors look for is proof that specific users adopted something and paid, not a screenshot of a polished interface.

VenturEdu
VenturEdu
Read Full Entry
 How to Get Your First 100 Customers in India
EntrepreneurshipSEP 14, 2026

How to Get Your First 100 Customers in India

Your first 100 customers come from the founder selling directly to one narrow segment through channels where that segment already gathers. They do not come from advertising, and they do not come from a launch. In India that usually means a mix of direct outreach, existing communities and WhatsApp groups, offline routes such as retailers, distributors, or trade associations, and referrals from the first few buyers. Expect to work individually for most of them. The point of the first hundred is not revenue. It is learning which channel repeats.Why are the first 100 customers different from the next thousand?The first hundred are bought with founder time. Everything after that is bought with a system. Confusing the two is the most common early growth mistake, because tactics that work at 20 customers, personal messages, custom demos, doing things by hand, are precisely the tactics that cannot scale, and tactics that scale, paid acquisition and content, produce almost nothing before you know who converts and why.There is a second difference that matters more. Early customers are buying you as much as the product. They are taking a risk on an unproven company, usually because they trust the person in front of them or because someone they trust made an introduction. Trust is the actual currency of the first hundred, and it is not purchasable at any budget.That is why founder-led selling is not a stage to rush through. Every conversation refines the pitch, exposes an objection you had not anticipated, and tells you whether the price holds. Delegating this before the pattern is clear means hiring someone to repeat a message that has not yet been proven to work.Where do your first customers actually come from?Pick two channels, not six. Running many channels badly produces activity without signal, and signal is the entire output of this phase.Direct outreachBuild a list of a hundred named individuals or companies that fit your segment precisely, then contact each one with a message that references something specific about them. Templates fail here because early adopters can smell a sequence. Realistic conversion is low, and that is fine: twenty replies and five conversations from a hundred messages is a working channel at this stage.Community accessFind where your segment already talks. In India that is often WhatsApp and Telegram groups, industry associations, alumni networks, LinkedIn, and local business communities rather than global platforms. Join before you sell, contribute for weeks, and let the credibility come first. Groups eject sellers quickly and remember them.Offline routesMany Indian categories still close offline. Retailers, distributors, clinic chains, coaching centres, dealer networks, and local trade bodies can put you in front of dozens of qualified buyers through one relationship. This is the channel founders from software backgrounds most often skip, and it is frequently the fastest one available.Referral loopsAsk every early customer for one introduction, at the moment they first get value rather than at the end of a billing cycle. Indian buying decisions carry heavy referral weight, particularly in B2B and in services, and a warm introduction converts at several times the rate of any cold channel you can run.How should founders sell in the first year?Personally, and without automation. Book the call yourself, run the demo yourself, and write the follow-up yourself. The goal of each conversation is to learn why someone did or did not buy, which is information a CRM sequence cannot collect for you.Keep a written log of every objection. After twenty conversations the objections repeat, and the repeated ones tell you what to change in the product, the price, or the positioning. Most founders discover their real positioning here rather than in a strategy session, because customers describe the product back to you in words you would not have chosen.Resist the urge to widen the segment when it gets hard. A narrow segment where you convert one in five beats a broad one where you convert one in fifty, even though the broad one feels like a bigger opportunity. If you have not yet fixed your segment, work through how to validate a startup idea in India before you start selling, because early sales into an undefined segment produce customers you cannot find more of.What makes early sales different in India?Global playbooks assume a self-serve buyer with a card and the authority to decide. Four local conditions break that assumption.Trust first: Buyers want reassurance before they want features, which is why a call, a physical address, a referral, or a visible team page often does more than a better landing page.Approval chains: The user is frequently not the decision maker. A family member, a procurement head, or a distributor may hold the actual authority, and selling to the user alone stalls at the last step.Language reality: Regional language matters in most segments outside metro B2B, and the shift from English is a conversion change rather than a marketing nicety.Channel habit: A large share of Indian buying conversations happen on WhatsApp and on phone calls, so a purchase flow that only works through a web form loses buyers who were ready.None of this means Indian buyers are harder to sell to. It means the friction sits in different places than a US playbook predicts, and the fixes are usually operational rather than technical.How should you price for the first 100 customers?Charge from the first customer. Free users teach you almost nothing about demand, and converting them later is harder than starting with a price, because you have taught them the value is zero.Discounting to win the early hundred is the specific trap. It produces customers who bought a price rather than a product, inflates a growth line that will not hold, and sets an anchor you cannot raise later. If the price is the objection, the more useful response is to narrow the offer rather than cut the number. Our guide on SaaS pricing strategy in India covers how early-stage founders should set that first price and what Indian willingness to pay actually looks like.Watch what each customer costs to win, including your own time, from the very first one. Founders who wait until the growth stage to work out unit economics for startups usually discover that their best-performing channel was never affordable.What should you track from customer one?Keep it to five numbers, in a spreadsheet, updated weekly.Source per customer: Which channel produced them, recorded at the moment they arrive rather than reconstructed later.Conversation to close: How many conversations each channel needs to produce one paying customer.Time to value: How long after buying a customer gets their first real outcome.Retention at 30 days: Whether they are still using or buying a month later.Referral rate: How many customers produce an introduction without being pushed.The channel that repeats is the one you scale. Strong retention and referrals across a narrow segment is also the earliest honest sign of traction, which is a different and higher bar than early sales alone. Our guide to product-market fit for startups sets out where that line actually sits.What stalls founders at ten customers?Friend sales: The first ten came from your own network, so the channel cannot be repeated.Segment drift: Selling to whoever will listen, which produces a customer base with no common thread.Early delegation: Hiring a salesperson before the pitch has been proven to convert.Channel spray: Running six channels at once and getting no readable signal from any.Silent churn: Adding customers monthly without noticing that last month's cohort stopped using.Free tier reliance: A large free base treated as traction when nobody has been asked to pay.Where do founders learn this with support?Early distribution is the part of company building that reads simplest and executes hardest, and it is the stage where a founder benefits most from someone who has run the same motion in the same market.VentureEdu, India's first full-time residential venture school, was launched by the Gurugram-based venture platform Fibonacci X and founded by Kulmani Rana. Its V-Unit model gives every venture a five-member mentor group that includes a dedicated go-to-market specialist alongside finance, brand, sector, and academic-industry mentors, so channel decisions get reviewed by someone with operating experience rather than tested purely by trial. Founders on the PGP in Entrepreneurship run this first-customer phase inside that structure over 14 months.The bottom lineGetting to a hundred customers in India is a founder's job, not a marketing budget's. Pick one narrow segment, choose two channels where that segment already gathers, sell personally, charge from the first customer, and track which channel repeats. Expect the offline and community routes to outperform the digital ones more often than a global playbook would suggest. When one channel produces customers reliably without you in every conversation, you have found the thing worth scaling. Until then, keep selling by hand.If you want an operator reviewing your channel plan before you spend on it, book a consultation with the VenturEdu team.Frequently asked questionsHow do startups get their first 100 customers?Through founder-led selling into one narrow segment, using direct outreach, existing communities, offline partners such as retailers or associations, and referrals from early buyers. Paid acquisition rarely works at this stage because you do not yet know who converts or what message moves them.How long does it take to get the first 100 customers?For most early-stage Indian startups, three to nine months. B2C and low-price services move faster. B2B moves slower because each sale involves multiple conversations and an approval chain. Speed matters less than knowing which channel produced each customer.Should a startup give its product away free to get early users?Generally no. Free users reveal interest, not demand, and converting them later is harder because you have already set the value at zero. Charging from the first customer produces smaller numbers and far better information about whether the business works.Which channels work best for early customers in India?Direct personal outreach, WhatsApp and Telegram communities, industry associations and alumni networks, offline routes such as retailers, distributors, and coaching centres, and referrals from existing customers. The right two depend on where your specific segment already gathers.When should a startup hire its first salesperson?After the founder has closed enough customers to know the pitch, the objections, and the conversion rate of at least one repeatable channel. Hiring earlier means paying someone to repeat a message that has not been proven, and the failure gets blamed on the hire rather than the plan.How many leads do you need for 100 customers?It depends on the channel, but a useful early planning assumption for cold outreach is that a hundred well-researched messages produce around twenty replies and five conversations. Referrals convert several times higher, which is why asking every early customer for one introduction changes the maths quickly.What is founder-led sales?Founder-led sales is the practice of the founder personally handling outreach, demos, and closing in the early stage, rather than delegating to a sales team. It exists because early customers buy trust in the founder as much as the product, and because every conversation generates product and positioning information.How do you know when to stop selling manually and start scaling?When one channel produces qualified customers consistently without the founder in every conversation, retention holds past thirty days, and unit economics work at the tested price. Scaling before those three are true multiplies a loss rather than a business.

VenturEdu
VenturEdu
Read Full Entry
How to Split Equity with a Co-Founder in India
LegalSEP 05, 2026

How to Split Equity with a Co-Founder in India

How to Split Equity with a Co-Founder in IndiaSplitting equity with a co-founder in India comes down to two decisions made together: what ratio each founder holds, and how that ownership is protected through vesting and a shareholders' agreement. Get both right at incorporation and you avoid the disputes that sink roughly a third of failed startups. Get either wrong and a co-founder who leaves in month six can walk away owning a quarter of a company they no longer build.This guide covers how to decide a fair split and how to protect it, including the India-specific steps most globally-templated advice skips: sweat equity, the shareholders' agreement, and the missing 83(b) election.What is a fair co-founder equity split?A fair equity split is one that reflects each founder's expected contribution over the next four years, not the work done before incorporation. Startups are won on execution, and almost all of that execution is still ahead of you on day one. The instinct to reward whoever "had the idea" is exactly the instinct that produces resentment later.There are three common structures. An equal split (50/50 for two founders, or 33/33/33 for three) signals partnership and trust, and equal splits among two-founder teams have become more common over the past decade. A weighted split (60/40, 70/30) reflects genuine differences in commitment, capital, or domain expertise. A role-based split adds a modest premium for the founder carrying CEO responsibility. None is automatically right. What matters is that the ratio maps honestly to contribution.A practical rule keeps most teams out of trouble: adjust for real, material differences, but do not over-index on any single factor. A founder who worked on the idea a year longer does not automatically deserve more equity for that alone; that is better handled through vesting than the split. Small premiums of 5 to 15 percent for cash invested, IP brought in, or clearly greater forward responsibility are reasonable. Large gaps built on past effort rarely are.Should you avoid a 50/50 split?A pure 50/50 split is not wrong, but it carries a specific risk that Indian founders hit repeatedly: deadlock. When two founders hold equal ownership and disagree on a major decision, there is no mechanism to break the tie. The most frequent cause of founder disputes after a Series A round in India traces back to clean 50-50 splits with no tiebreaker.The fix is not necessarily an unequal split. It is governance. Even with a 50/50 ownership ratio, designate one founder as the tiebreaker on operational decisions, and build a deadlock-resolution mechanism into your agreement, such as a casting vote for the CEO, an independent director, or a defined escalation for major decisions like a sale or a pivot. That way you keep the signal of equal partnership without leaving the company ungovernable.Once the ratio feels equitable, stress-test it against dilution before you treat it as final. Model a 10 percent ESOP pool, then a 20 percent seed round, then a further 20 percent at Series A. A founder comfortable with 40 percent at incorporation may feel very different when that number sits near 23 percent post-Series A. If you are heading toward a formal raise or a startup accelerator in India, working through the maths in advance is what keeps the split feeling fair once funding begins.Why does vesting matter more than the ratio?Vesting is what makes any split safe, and it protects the ratio you just agreed. Without it, ownership is fixed the moment shares are issued, so a co-founder who departs after six months keeps their full stake while the remaining team builds all the value over the following years. Investors treat missing vesting as a red flag for exactly this reason, and about one in four founding teams loses a co-founder by year four.The standard structure is four-year vesting with a one-year cliff. No equity vests during the first year. At the twelve-month mark, 25 percent vest at once, and the remainder vests monthly or quarterly over the following three years. The cliff is the trial period made concrete: if a co-founder leaves before a year, they leave with nothing, which is precisely the protection you want when you have known each other only a few months.Agree the vesting terms in the same conversation as the ratio, not afterward. Bolting vesting on later, once someone already feels they "own" a number, is where negotiations turn sour. Decide acceleration terms up front too: double-trigger acceleration, which releases unvested equity only on both an acquisition and the founder's termination, is the market standard most investors prefer.How do you protect the split legally in India?The agreement that makes all of this enforceable is the shareholders' agreement (SHA), backed by the company's Articles of Association. This is the single most important founder document, and it is where founders' agreements in India do their real work. The SHA sets out the equity split, the vesting schedule, transfer restrictions, and, critically, the company's right to repurchase unvested shares from a departing co-founder. Vesting without a documented repurchase mechanism is a promise with no teeth.India also has an instrument with no clean US equivalent: sweat equity shares under Section 54 of the Companies Act, 2013. These let a company issue shares to a founder or key contributor for intellectual property, know-how, or value added rather than cash, which helps when a co-founder brings IP the company cannot yet pay for. The rules are strict: a special resolution, a registered valuer's report, at least one year of business existence, and a lock-in period. Startups get an important concession, the ability to issue sweat equity up to 50 percent of paid-up capital within five years of incorporation, against the general 25 percent ceiling. Get one element wrong and the allotment can be invalid, so run this with a company secretary, not from a template.Because equity structuring is where founder decisions meet company law, many first-time founders work through it with experienced mentors before signing. Structured programs that pair founders with operators and legal guidance, such as the mentorship built into a residential PGP in Entrepreneurship, exist partly to get these foundational decisions right the first time. For the wider set of registrations and filings that surround this, a complete startup legal checklist covers the ground beyond equity.What are the tax implications of founder equity in India?The key India-specific point is what is missing. In the US, an 83(b) election lets founders be taxed on restricted stock at purchase, when the value is near zero, rather than as it vests at a higher value. India has no 83(b) equivalent. The practical consequence is clear: founders should purchase their shares at incorporation, when fair market value is nominal, typically the ₹10 face value per share. Delay means a higher FMV at the time of purchase and a higher immediate tax bill, so the timing is not a formality.This is one more reason to settle the split, vesting, and share purchase together and early, while the company is worth almost nothing. Restructuring equity after formation is possible but grows complex quickly, needing board approval, fresh documentation, and potential tax for a founder giving up shares. The cheapest, cleanest moment to get ownership right is the day you incorporate.The bottom lineSplitting equity with a co-founder in India is not about finding a magic percentage. It is about agreeing a ratio that reflects future contribution, protecting it with four-year vesting and a one-year cliff, and documenting it in a shareholders' agreement with a repurchase right. Add the India-specific realities, a tiebreaker to avoid 50/50 deadlock, sweat equity done properly under Section 54, and share purchase at face value because there is no 83(b) relief, and you have a founding structure that survives both a departure and a diligence process. Decide it together, write it down, and do it on day one.If you want operator and legal guidance while you set up these founding decisions, book a consultation with the VenturEdu team.Frequently asked questionsHow much equity should a co-founder get in India?It depends on contribution over the next four years, not past work. Two full-time founders bringing similar value often split equally, while material differences in commitment, capital, or domain expertise justify a weighted split, usually with a premium of 5 to 15 percent rather than a large gap.What is the standard vesting schedule for founders in India?Four-year vesting with a one-year cliff is the market standard. No equity vests in the first year, then 25 percent vests at the twelve-month mark, and the rest vests monthly or quarterly over the next three years. It protects the company if a co-founder leaves early.Is a 50/50 equity split a bad idea?Not inherently, but it risks deadlock when founders disagree. If you split equally, add a governance mechanism, such as a CEO tiebreaker on operational decisions or an independent director, since clean 50-50 splits with no tiebreaker are a common source of founder disputes in India after Series A.What is a sweat equity share in India?A sweat equity share is equity issued under Section 54 of the Companies Act, 2013 to a director or employee for intellectual property, know-how, or value added rather than cash. It requires a special resolution and a registered valuer report, and startups can issue up to 50 percent of paid-up capital within five years of incorporation.Can founder equity be changed after the company is formed?Yes, but it becomes complex. Restructuring requires board approval, new documentation, possible shareholder consent, and can create tax consequences for a founder giving up shares. It is far cheaper and simpler to get the split and vesting right at incorporation.Do Indian founders need to file an 83(b) election?No. The 83(b) election is a US tax provision and has no Indian equivalent. Instead, Indian founders should purchase their shares at incorporation when fair market value is nominal, around the ₹10 face value, to avoid a higher tax bill from buying shares later at a higher valuation.What document protects a co-founder equity split in India?The shareholders' agreement (SHA), read with the Articles of Association, is the key document. It records the equity split, vesting schedule, transfer restrictions, and the company's right to repurchase unvested shares from a departing founder, which is what makes vesting enforceable.What happens to equity if a co-founder leaves early?With proper vesting and an SHA, the departing co-founder keeps only their vested shares, and the company can repurchase the unvested portion. Without vesting, they keep their full original stake regardless of how little time they contributed, which is the exact outcome vesting exists to prevent.

VenturEdu
VenturEdu
Read Full Entry
 Pitch Deck for Investors in India: The 12 Slides You Need
EntrepreneurshipSEP 01, 2026

Pitch Deck for Investors in India: The 12 Slides You Need

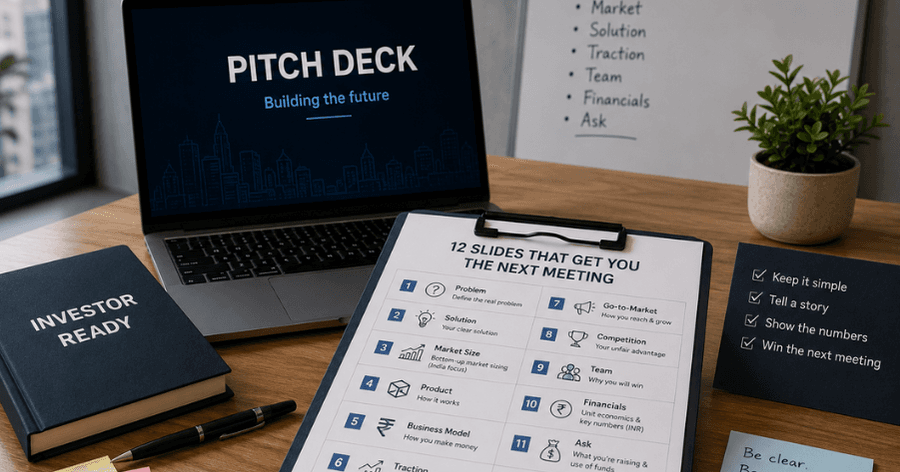
Pitch Deck for Investors in India: The 12 Slides You NeedA pitch deck for investors in India has one job: earn the next meeting. An Indian angel or seed fund sees thousands of decks a year and spends under three minutes on a cold one, so every slide has to justify its place. This guide walks the standard slide arc in order, with the India-specific expectations that most US templates miss: bottom-up market sizing, rupee-denominated unit economics, and the governance signals that clean, compliant startups get credit for.Get the structure right and the deck does what it is meant to do: filter you in, not out.How many slides should a pitch deck have?Keep an early-stage pitch deck to 12 to 15 slides. This isn't arbitrary. Startup India's own pitch guidelines recommend an initial presentation of no more than 12 to 15 slides, and funded-deck data lands in the same range: the decks investors actually read through to the end average around 12 pages.Slide count also flexes with how the deck is used. A cold-email version runs 10 to 12 slides, a live presentation deck 12 to 15, and a later-stage diligence deck can grow an appendix to 15 to 20. Across all of them the arc stays the same. What grows is the appendix, not the story. Send a PDF, never an editable file, and keep it lean.The reason the order matters is that each slide answers the logical question the previous one raises. Investors read a deck against a mental checklist, and the standard sequence matches that checklist. Here is the arc.The 12 slides an Indian investor deck needs1. TitleOne line that says exactly what you do, plus your logo, and the raise in a phrase. Not a tagline puzzle. The strongest one-liners read like the email that got you the meeting: category, traction, ask. For example, "B2B invoicing SaaS, ₹3.2L MRR growing 18% month on month, raising ₹6 crore seed." Add your name, city, and contact details so the deck works standalone.2. ProblemName the real, specific pain your target customer feels, in their words. Indian investors are wary of invented problems dressed up with big numbers. Ground it: who has this problem, how often, and what it costs them today. One sharp problem beats three vague ones.3. SolutionShow how you solve it, simply. This is not the place for a feature dump. State the core insight and what your product actually does, ideally with a single screenshot or a one-line before-and-after. The test is whether a non-expert understands the value in ten seconds.4. Market sizeThis is the slide that separates credible Indian decks from the rest. Build your market bottom-up, not top-down. The fastest way to lose a room is the "1% of 140 crore people" maths. Instead, size it from the ground: number of realistic customers, multiplied by what they actually pay, in rupees.Localise the number using Indian sources investors trust: RBI data, IBEF sector reports, and category-level data from Venture Intelligence or similar. Investors evaluating a ₹10 to 50 crore seed round want to see the India opportunity sized independently before any global projection. Present TAM, SAM, and SOM, but spend your credibility on the SOM, the slice you can realistically win.5. ProductShow the product working. A short flow of two or three screenshots, a simple diagram, or a demo link. For pre-product startups, a clickable prototype or mockup is fine. The goal is to make the solution concrete and prove you have built, or can build, the thing.6. TractionFor early-stage decks, this is often the slide investors jump to first, and the bar is evidence quality, not size. A smaller number with strong retention beats a bigger number that is flat. ₹1.5 lakh MRR with month-six retention above 80% is more fundable than ₹4 lakh MRR with churning cohorts.Show a cohort or retention curve, revenue trend, and any signal of real demand: paying customers, pilot results, growth rate, waitlist, partnerships. Avoid vanity metrics. In India especially, three traps kill credibility here: counting GMV as revenue, annualising one good month, and leaning on downloads instead of usage. Show numbers that will survive diligence, because a fund's analyst will rebuild them from your data room anyway.7. Business modelHow you make money, in plain terms. Revenue streams, pricing, and unit economics. Tie it to real figures rather than "we will monetise later." The metric relationship investors look for is LTV comfortably exceeding CAC, with a payback period that makes sense for your category. Present unit economics in the Indian context: what a customer costs to acquire here, and what they are worth over time. If unit economics are unfamiliar territory, the best startup courses in India cover the financial fundamentals every founder needs before a raise.8. CompetitionShow you know the landscape, honestly. A simple two-axis positioning map or a feature matrix comparing you to real alternatives, including the "do nothing" option and any incumbent workarounds. Claiming you have no competition reads as naivety. What investors want is a clear, defensible reason you win: a wedge, an unfair advantage, or a structural edge.9. Go-to-marketHow you will reach customers and grow. Channels, the motion (self-serve, sales-led, distribution partners), and early evidence of what is working. For Indian markets, be concrete about the realities of your channel, whether that is regional expansion, vernacular reach, offline-to-online, or a specific distribution partnership. Show CAC by channel if you have it, and your organic-versus-paid mix.10. TeamWhy you, and why now. Founders' names, roles, and the specific experience that makes you the right people to build this. Mention shareholding or co-founder split at a high level. Indian investors are explicit about this: a part-time founding team is a common reason decks get passed over. Show full commitment and complementary skills, and name key advisors if they add real weight. If you are still assembling your team and traction, joining a startup accelerator in India can help you build both before you raise.11. FinancialsA realistic three-to-five-year projection in rupees, with the assumptions visible. Investors are less interested in the exact numbers than in whether your assumptions are sane and your logic holds. Include the metrics that matter for your model: revenue, gross margin, burn rate, and runway. Optimism is fine. Fantastical is not. Show the path, and be candid about what you do not yet know.12. The askEvery deck must end with a clear, specific task, and this is the slide founders most often fumble. State how much you are raising, in rupees, and exactly what it buys: the milestone the money takes you to. "Raising ₹6 crore to reach ₹1 crore ARR and Series A readiness in 18 months" is an ask. A number with no milestone is not. Break down the use of funds at a high level, mention your instrument if relevant, and make the next step obvious. If you are pre-product and not yet ready to name a raise, a startup incubator in India is often the better first step before a formal ask.The India-specific expectations most templates missBeyond the slides themselves, a few things separate decks that get funded in India from decks that copy a Silicon Valley template.Bottom-up market maths, always. Top-down percentages of India's population are the single most common thing that kills a deck. Size from real customers and real prices.Metrics that survive diligence. Do not count GMV as revenue, do not annualise a single good month, and do not lean on vanity numbers. A stale or inflated figure in a live raise reads worse than a smaller honest one.Governance hygiene. Clean, compliant startups get quiet credit. A cap table without clutter, proper company structure, and CA-clean books signal a company that will not create surprises in due diligence. It also matters for government-backed routes: a pitch deck is part of the documentation for the Startup India Seed Fund Scheme and DPIIT-linked benefits, so the same deck often does double duty. This is where the legal and compliance groundwork you did early pays off.Standalone readability. US decks are often just a peg for conversation. In India, the average investor expects a more detailed deck that can be read and understood on its own, without you in the room.The one-line email above the deck. The cold email that carries your deck matters as much as slide one. Category, traction, and ask in a single sentence is often what earns the open.Common pitch deck mistakes to avoidThe India-specific pitfalls above (top-down sizing, diligence-proof metrics, governance) cause most rejections, but a few delivery and process mistakes quietly sink otherwise-good decks too:No milestone: an ask that states a number without the outcome the money buys.Cluttered cap table: a messy ownership structure that signals future diligence pain.Too long: a deck that buries the thesis past slide 15.Stale numbers: an outdated traction figure during a live raise, when a smaller current one reads better.Slow follow-up: going silent instead of one polite bump after five to seven days.Over-explaining: trying to preempt every objection instead of sparking good questions.Fix these and the fundamentals carry the deck. A tight 12-slide deck that invites conversation will always beat a 25-slide deck that tries to answer everything in advance.One more practical point: the deck earns the meeting, but the meeting is won in the room. Founders who have pitched repeatedly to real investors, whether through an accelerator, a demo day, or structured investor-readiness practice, tend to handle the follow-up questions far better than those pitching cold for the first time. Programs that build in regular investor exposure, such as VenturEdu's demo days and its network of 100+ investors and mentors, give founders that repetition before it counts. This is one reason a residential PGP in Entrepreneurship suits founders who want reps with real investors, not just a polished file.The bottom lineA pitch deck for investors in India is not a brochure. It is a filtering tool built to answer, in order, the questions every investment committee will ask anyway. Keep it to 12 to 15 slides, follow the arc, size your market bottom-up, put every metric in rupees, and end with a specific, milestone-backed ask. Do that, and your deck does its one job: it earns you the next conversation.If you want structured support turning your idea into an investable venture, from the deck to the demo day, book a consultation with the VenturEdu team.Frequently asked questionsWhat should a pitch deck for investors in India include? A standard Indian investor deck includes 12 core slides: title, problem, solution, market size, product, traction, business model, competition, go-to-market, team, financials, and the ask. Startup India recommends keeping the initial presentation to 12 to 15 slides.How many slides should a startup pitch deck have? Keep an early-stage deck to 12 to 15 slides. A cold-email version can drop to 10 to 12, while a later-stage diligence deck can extend to 15 to 20 with an appendix. Funded decks most commonly land around 12 slides.How do you calculate market size for an Indian pitch deck? Build it bottom-up: estimate your realistic number of customers and multiply by what they actually pay, in rupees. Localise the numbers using sources like RBI data, IBEF reports, and Venture Intelligence. Avoid top-down "percentage of India's population" maths, which investors distrust.What traction do early-stage Indian investors want to see? Evidence quality matters more than size. Show retention or cohort curves, revenue trend, and real demand signals like paying customers or pilot results. A smaller MRR with strong retention beats a larger one that is churning. Avoid vanity metrics and never count GMV as revenue.What is the most important slide in a pitch deck? There is no single answer, but early-stage investors often weigh traction and team most heavily, and the ask slide is the one founders most often get wrong. Every deck must end with a clear, rupee-denominated task tied to a specific milestone.Should I send my pitch deck as a PowerPoint or PDF? Send a PDF, never an editable file. Keep the file size reasonable and the deck lean. Pair it with a one-line email covering your category, traction, and ask, since that sentence often determines whether the deck gets opened.Do I need a pitch deck for Startup India or DPIIT recognition?Yes. A pitch deck is part of the documentation for Startup India Seed Fund and DPIIT-linked benefits such as 80-IAC tax exemption. Startups at the early-traction or scaling stage are generally expected to provide one, following the 12 to 15 slide structure.How long should an investor spend reading my deck? Assume under three minutes for a cold deck, and often under two for a seed deck. That time pressure is exactly why the slide order matters and why every slide must earn its place.

VenturEdu
VenturEdu
Read Full Entry
Startup School in India: What It Means and Which One Fits You
EntrepreneurshipSEP 01, 2026

Startup School in India: What It Means and Which One Fits You

Search "startup school in India" and you'll get several different answers, a free online course from Y Combinator, a two-week AI program from Google, a 45-day on-campus bootcamp in Gurugram, or a 14-month residential venture school. They share two words but they are not the same thing, and picking the wrong model wastes months you don't have.This guide explains what a startup school actually is, how it differs from a course, an accelerator, and an incubator, and how to choose the model that fits where you are as a founder. If you already know you want the full, capital-backed, build-a-real-company version, we'll point you there too.What is a startup school?A startup school is a structured program that teaches you to build a company by having you actually build one, not by lecturing you on business theory. The term spans a spectrum, from free online courses to full-time residential programs, but the common thread is founder-first, execution-led learning: ideation, customer validation, building a minimum viable product (MVP), fundraising, and pitching to investors.The phrase took off largely because of Y Combinator's Startup School, a free online course the accelerator launched in 2017 to give founders anywhere access to its playbook. Since then, "startup school" has become a loose category in India covering everything from government learning programs to premium residential venture schools, which is exactly why the search results feel scattered.The useful way to think about it: every startup school sits somewhere on a depth spectrum. At the shallow end, it's a free course you fit around a day job. At the deep end, it's a full-time program that consolidates learning, mentorship, and capital under one roof and expects you to graduate with a fundable venture. Where you should enter depends on your stage and your commitment.Startup school vs. course vs. accelerator vs. incubatorIn short: a course teaches founder skills, an incubator shapes a raw idea, an accelerator speeds up an existing product, and a residential startup school combines learning, building, mentorship, and capital for a founder going full-time. The differences come down to your stage.ModelWhat it doesTypical lengthTakes equity?Best forOnline courseTeaches founder skills through structured contentWeeksNoIdea-stage, exploring, part-timeStartup school (residential)Combines education, building, mentorship, and capitalMonthsSometimes / investsCommitted, full-time first-time foundersAcceleratorSpeeds up an existing product toward fundraising3–6 monthsUsually yesFounders with a product and early tractionIncubatorNurtures a raw idea toward a first productOpen-endedOften noVery early, pre-product foundersThe decisive word is stage. A startup accelerator in India assumes you already have something to accelerate, a working product and early users. A startup incubator in India assumes you're earlier, shaping a raw idea. A course teaches you to think like a founder. A residential startup school is built for the founder who has decided to go full-time but lacks the infrastructure, capital, mentors, legal, design, growth, to execute properly.Choosing a format built for a stage you haven't reached is the most common early-stage mistake. A first-time founder with only an idea who joins an accelerator gives up equity too early and struggles to keep pace with a cohort built around growth.Types of startup schools in IndiaIndia's "startup school" landscape falls into four groups, each serving a different founder.Free online courses. Y Combinator Startup School runs a multi-week online cohort with partner sessions, a curriculum on product, growth, and fundraising, and a co-founder matching network of over 100,000 people; recent Indian participants also received AI and cloud credits. For a full breakdown, see our guide to the best startup courses in India. Google for Startups' Startup School India is a fully funded online program teaching non-technical founders to build AI-powered prototypes using tools like Gemini within AI Studio. Both are excellent, free, and network-first, but short and part-time by design.Government learning programs. The Startup India Learning Program, backed by DPIIT (Department for Promotion of Industry and Internal Trade) and delivered with Invest India, is a free four-week course covering registration, funding schemes, compliance, and mentorship. It pairs naturally with DPIIT recognition under Startup India, which unlocks tax benefits and easier compliance. Policy-first, and ideal for getting oriented.Short on-campus bootcamps. A newer wave of Indian programs runs intensive, in-person cohorts that compress idea to MVP to pitch into weeks: the Indian Startup School's 45-day Gurugram bootcamp, Mesa School of Business in Bengaluru, and others. These suit founders who want momentum and a peer group without a long commitment.Residential venture schools. At the deep end sits the full-time, live-in model that combines structured learning, hands-on venture building, mentorship, and committed capital over many months. This is the newest and most integrated category in India, built for founders ready to make company-building their only job. VenturEdu is the leading example (more below).How much does a startup school in India cost?It ranges from completely free to several lakh rupees, and the price tracks the depth.Free options cost nothing, with optional certificates around ₹1,000–1,500: Y Combinator Startup School, Google for Startups Startup School India, the Startup India Learning Program, and NPTEL's entrepreneurship course from IIT Madras. These deliver real value at the idea stage.Short on-campus bootcamps typically run from tens of thousands of rupees up to a lakh or two, depending on duration and intensity. Full residential venture schools and IIM-level programs sit higher, reflecting months of full-time mentorship, infrastructure, and, in the best cases, direct access to capital. For a residential program, the right question isn't the sticker price but the return: mentor quality, and whether the program actually puts money behind its graduates rather than only introducing them to investors.How to choose the right startup school for your stageDon't filter by brand name. Filter by your stage, your available time, and whether you need a credential or real capital.Idea stage (0–6 months in). You're exploring and need breadth, not depth. Start free: Y Combinator Startup School, Google's Startup School India, or the Startup India Learning Program. Zero financial risk, and enough to test whether you're serious.Early stage (6–18 months in). You have a validated concept and need execution skills and structure. A short on-campus bootcamp or a strong online specialization builds momentum and a peer network without a multi-year commitment.Ready to go full-time. You've decided to build and need the whole stack, capital, mentors, legal, design, growth, in one place. This is where a residential venture school earns its cost, because network and committed capital, not curriculum, become the product.One national reality worth naming: 51% of India's DPIIT-recognized startups now originate from Tier II and III cities, yet most premium on-campus programs cluster in metros. If you're outside Bengaluru, Mumbai, Delhi, or Gurugram, free online startup schools aren't a compromise: the quality gap has largely closed, and they're often the smartest starting point before you commit to anything residential.Where VenturEdu fitsIf you're a first-time founder ready to build full-time, VenturEdu is India's first full-time residential venture school, purpose-built for the deep end of this spectrum.Launched by the Gurugram-based venture platform Fibonacci X and founded by Kulmani Rana, VenturEdu runs a 14-month PGP in Entrepreneurship where you arrive with an idea and graduate with an investable venture. Three things separate it from a short course or a conventional accelerator:The V-Unit mentorship model. Every idea gets a dedicated five-member mentor group, a go-to-market specialist, a financial advisor, a brand advisor, a sector mentor with Series A+ experience, and an academic-industry partner. A focused advisory board around your venture, not a group session with forty other founders.Committed capital, not just introductions. A seed corpus of roughly ₹15 crore backs the program, with the top 30% of each cohort eligible for direct funding consideration, plus access to a 100+ VC network and regular investor demo days.Residential and cross-border. An intensive Gurugram campus paired with a six-week international immersion in Dubai or Singapore, so you think about scale and global markets during the program, not after.VenturEdu is deliberately not for casual exploration. If you're still testing whether entrepreneurship is for you, start with a free program like Y Combinator Startup School and validate your commitment first. But if you've decided to build and need the infrastructure to do it properly, a residential venture school is the model that fits, and VenturEdu is the one purpose-built for it in India.The bottom line"Startup school" isn't one thing, it's a spectrum from a free weekend course to a full-time residential venture school. The best one for you isn't the most famous brand; it's the one that matches your stage. Start free when you're exploring, add structure when you're validating, and commit to a residential venture school when you're ready to build full-time and need capital and mentors in one place. Match the model to the moment, and the choice becomes clear.Still weighing your options? Our guide on how to choose the right entrepreneurship course in India walks through the decision in more detail. And if you're at that full-time, ready-to-build stage, explore VenturEdu's PGP in Entrepreneurship, or book a consultation to see whether the next cohort is the right fit.Frequently asked questionsWhat is a startup school?A startup school is a structured program that teaches founders to build a company by actually building one, covering ideation, validation, MVP development, fundraising, and pitching. The term spans free online courses to full-time residential venture schools.What is the difference between a startup school and an accelerator? A startup school, especially the residential kind, combines education, hands-on building, mentorship, and often capital for founders building from an idea. An accelerator takes an existing product with early traction through a short, fixed cohort toward fundraising, usually in exchange for equity.Is Y Combinator Startup School free? Yes. Y Combinator's Startup School is a free online program open to founders at any stage, with curriculum, partner sessions, and a large co-founder matching network. YC has also hosted a Startup School event in Bengaluru.What is Google's Startup School India? Google for Startups runs Startup School India, a fully funded online program that teaches founders, particularly non-technical ones, to build AI-powered prototypes using Google's AI tools. It's free, delivered through online workshops and on-demand content.Are startup schools worth it for first-time founders in India? They can be, when the program teaches validated frameworks and connects you to real networks and capital. The right choice depends on your stage: free courses for idea-stage exploration, and a residential venture school when you're ready to build full-time.How much does a startup school in India cost? Anywhere from free (Y Combinator, Google for Startups, Startup India Learning Program, NPTEL) to a few lakh rupees for short on-campus bootcamps, up to higher fees for full residential venture schools and IIM-level programs. Cost tracks depth and time commitment.Which startup school is best for someone ready to build full-time? For founders committing full-time, a residential venture school is the strongest fit. VenturEdu's 14-month PGP in Entrepreneurship is India's first residential venture school, offering the V-Unit mentor model, a ₹15 crore seed corpus, a 100+ VC network, and an international immersion.Do I need a technical or business background to join a startup school? No. Most startup schools, including free programs and VenturEdu's PGP, accept founders from any background, engineering, commerce, humanities, or family business. Google's Startup School India is specifically designed for non-technical founders.

VenturEdu
VenturEdu
Read Full Entry

Come with an idea and graduate with an investable venture in 14 months

We bridge the gap between knowledge and execution helping you turn ideas into outcomes

PGP in Entreprenuership
VentureEdu Logo
VentureEdu

Turn Ideas Into Real Businesses

FacebookInstagramLinkedInXYouTube

Newsletter

Subscribe to get notifies on daily, insights and updates from venturedu

Contact info

MPD Tower, Golf Course Road, Gurugram, Haryana 122009

© 2026 VenturEdu. All rights reserved.