Splitting equity with a co-founder in India comes down to two decisions made together: what ratio each founder holds, and how that ownership is protected through vesting and a shareholders' agreement. Get both right at incorporation and you avoid the disputes that sink roughly a third of failed startups. Get either wrong and a co-founder who leaves in month six can walk away owning a quarter of a company they no longer build.
This guide covers how to decide a fair split and how to protect it, including the India-specific steps most globally-templated advice skips: sweat equity, the shareholders' agreement, and the missing 83(b) election.
What is a fair co-founder equity split?
A fair equity split is one that reflects each founder's expected contribution over the next four years, not the work done before incorporation. Startups are won on execution, and almost all of that execution is still ahead of you on day one. The instinct to reward whoever "had the idea" is exactly the instinct that produces resentment later.
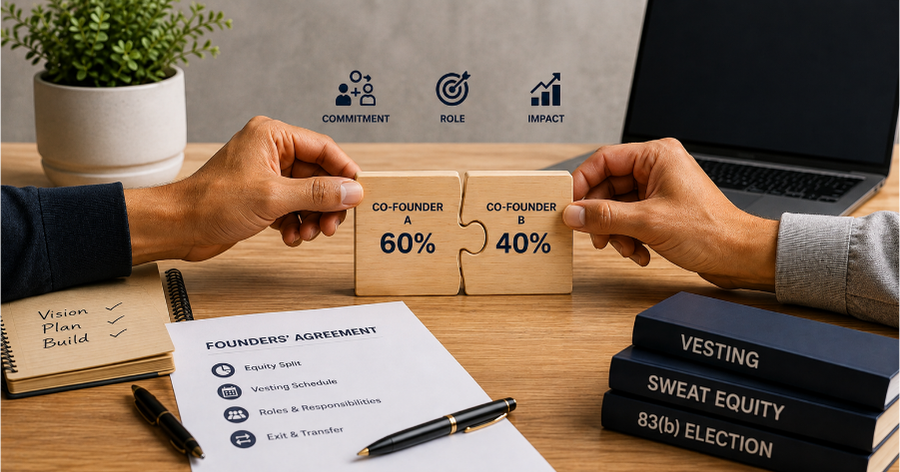
There are three common structures. An equal split (50/50 for two founders, or 33/33/33 for three) signals partnership and trust, and equal splits among two-founder teams have become more common over the past decade. A weighted split (60/40, 70/30) reflects genuine differences in commitment, capital, or domain expertise. A role-based split adds a modest premium for the founder carrying CEO responsibility. None is automatically right. What matters is that the ratio maps honestly to contribution.
A practical rule keeps most teams out of trouble: adjust for real, material differences, but do not over-index on any single factor. A founder who worked on the idea a year longer does not automatically deserve more equity for that alone; that is better handled through vesting than the split. Small premiums of 5 to 15 percent for cash invested, IP brought in, or clearly greater forward responsibility are reasonable. Large gaps built on past effort rarely are.
Should you avoid a 50/50 split?
A pure 50/50 split is not wrong, but it carries a specific risk that Indian founders hit repeatedly: deadlock. When two founders hold equal ownership and disagree on a major decision, there is no mechanism to break the tie. The most frequent cause of founder disputes after a Series A round in India traces back to clean 50-50 splits with no tiebreaker.
The fix is not necessarily an unequal split. It is governance. Even with a 50/50 ownership ratio, designate one founder as the tiebreaker on operational decisions, and build a deadlock-resolution mechanism into your agreement, such as a casting vote for the CEO, an independent director, or a defined escalation for major decisions like a sale or a pivot. That way you keep the signal of equal partnership without leaving the company ungovernable.
Once the ratio feels equitable, stress-test it against dilution before you treat it as final. Model a 10 percent ESOP pool, then a 20 percent seed round, then a further 20 percent at Series A. A founder comfortable with 40 percent at incorporation may feel very different when that number sits near 23 percent post-Series A. If you are heading toward a formal raise or a startup accelerator in India, working through the maths in advance is what keeps the split feeling fair once funding begins.
Why does vesting matter more than the ratio?
Vesting is what makes any split safe, and it protects the ratio you just agreed. Without it, ownership is fixed the moment shares are issued, so a co-founder who departs after six months keeps their full stake while the remaining team builds all the value over the following years. Investors treat missing vesting as a red flag for exactly this reason, and about one in four founding teams loses a co-founder by year four.
The standard structure is four-year vesting with a one-year cliff. No equity vests during the first year. At the twelve-month mark, 25 percent vest at once, and the remainder vests monthly or quarterly over the following three years. The cliff is the trial period made concrete: if a co-founder leaves before a year, they leave with nothing, which is precisely the protection you want when you have known each other only a few months.
Agree the vesting terms in the same conversation as the ratio, not afterward. Bolting vesting on later, once someone already feels they "own" a number, is where negotiations turn sour. Decide acceleration terms up front too: double-trigger acceleration, which releases unvested equity only on both an acquisition and the founder's termination, is the market standard most investors prefer.
How do you protect the split legally in India?
The agreement that makes all of this enforceable is the shareholders' agreement (SHA), backed by the company's Articles of Association. This is the single most important founder document, and it is where founders' agreements in India do their real work. The SHA sets out the equity split, the vesting schedule, transfer restrictions, and, critically, the company's right to repurchase unvested shares from a departing co-founder. Vesting without a documented repurchase mechanism is a promise with no teeth.
India also has an instrument with no clean US equivalent: sweat equity shares under Section 54 of the Companies Act, 2013. These let a company issue shares to a founder or key contributor for intellectual property, know-how, or value added rather than cash, which helps when a co-founder brings IP the company cannot yet pay for. The rules are strict: a special resolution, a registered valuer's report, at least one year of business existence, and a lock-in period. Startups get an important concession, the ability to issue sweat equity up to 50 percent of paid-up capital within five years of incorporation, against the general 25 percent ceiling. Get one element wrong and the allotment can be invalid, so run this with a company secretary, not from a template.
Because equity structuring is where founder decisions meet company law, many first-time founders work through it with experienced mentors before signing. Structured programs that pair founders with operators and legal guidance, such as the mentorship built into a residential PGP in Entrepreneurship, exist partly to get these foundational decisions right the first time. For the wider set of registrations and filings that surround this, a complete startup legal checklist covers the ground beyond equity.
What are the tax implications of founder equity in India?
The key India-specific point is what is missing. In the US, an 83(b) election lets founders be taxed on restricted stock at purchase, when the value is near zero, rather than as it vests at a higher value. India has no 83(b) equivalent. The practical consequence is clear: founders should purchase their shares at incorporation, when fair market value is nominal, typically the ₹10 face value per share. Delay means a higher FMV at the time of purchase and a higher immediate tax bill, so the timing is not a formality.
This is one more reason to settle the split, vesting, and share purchase together and early, while the company is worth almost nothing. Restructuring equity after formation is possible but grows complex quickly, needing board approval, fresh documentation, and potential tax for a founder giving up shares. The cheapest, cleanest moment to get ownership right is the day you incorporate.
The bottom line
Splitting equity with a co-founder in India is not about finding a magic percentage. It is about agreeing a ratio that reflects future contribution, protecting it with four-year vesting and a one-year cliff, and documenting it in a shareholders' agreement with a repurchase right. Add the India-specific realities, a tiebreaker to avoid 50/50 deadlock, sweat equity done properly under Section 54, and share purchase at face value because there is no 83(b) relief, and you have a founding structure that survives both a departure and a diligence process. Decide it together, write it down, and do it on day one.
If you want operator and legal guidance while you set up these founding decisions, book a consultation with the VenturEdu team.
Frequently asked questions
How much equity should a co-founder get in India?
It depends on contribution over the next four years, not past work. Two full-time founders bringing similar value often split equally, while material differences in commitment, capital, or domain expertise justify a weighted split, usually with a premium of 5 to 15 percent rather than a large gap.
What is the standard vesting schedule for founders in India?
Four-year vesting with a one-year cliff is the market standard. No equity vests in the first year, then 25 percent vests at the twelve-month mark, and the rest vests monthly or quarterly over the next three years. It protects the company if a co-founder leaves early.
Is a 50/50 equity split a bad idea?
Not inherently, but it risks deadlock when founders disagree. If you split equally, add a governance mechanism, such as a CEO tiebreaker on operational decisions or an independent director, since clean 50-50 splits with no tiebreaker are a common source of founder disputes in India after Series A.
What is a sweat equity share in India?
A sweat equity share is equity issued under Section 54 of the Companies Act, 2013 to a director or employee for intellectual property, know-how, or value added rather than cash. It requires a special resolution and a registered valuer report, and startups can issue up to 50 percent of paid-up capital within five years of incorporation.
Can founder equity be changed after the company is formed?
Yes, but it becomes complex. Restructuring requires board approval, new documentation, possible shareholder consent, and can create tax consequences for a founder giving up shares. It is far cheaper and simpler to get the split and vesting right at incorporation.
Do Indian founders need to file an 83(b) election?
No. The 83(b) election is a US tax provision and has no Indian equivalent. Instead, Indian founders should purchase their shares at incorporation when fair market value is nominal, around the ₹10 face value, to avoid a higher tax bill from buying shares later at a higher valuation.
What document protects a co-founder equity split in India?
The shareholders' agreement (SHA), read with the Articles of Association, is the key document. It records the equity split, vesting schedule, transfer restrictions, and the company's right to repurchase unvested shares from a departing founder, which is what makes vesting enforceable.
What happens to equity if a co-founder leaves early?
With proper vesting and an SHA, the departing co-founder keeps only their vested shares, and the company can repurchase the unvested portion. Without vesting, they keep their full original stake regardless of how little time they contributed, which is the exact outcome vesting exists to prevent.